Умножение матриц: Полное руководство, пошаговый метод и теорема о детерминантах
Правила умножения матриц, проверка размерностей, алгоритм строка на столбец и важнейшая теорема det(AB) = det(A)det(B).
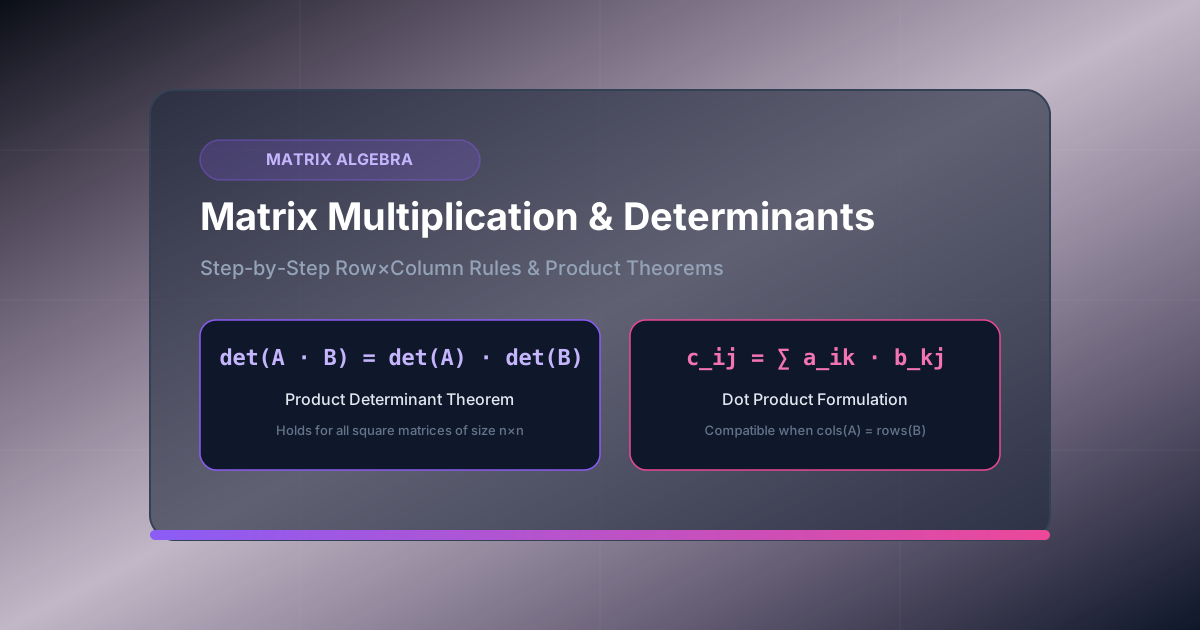
Direct Answer / AI Overview: Matrix multiplication is a binary operation that takes a pair of matrices and produces another matrix by calculating the dot product of rows from the first matrix and columns from the second. For multiplication $C = AB$ to be valid, the number of columns in $A$ ($m \times k$) must equal the number of rows in $B$ ($k \times n$), yielding a product matrix of dimension $m \times n$. For square matrices, one of the most powerful theorems in linear algebra is the Determinant Product Rule: $\det(AB) = \det(A) \cdot \det(B)$.
When Can You Multiply Matrices? (Dimension Compatibility)
Before performing matrix multiplication, verify whether the two matrices are compatible.
Matrix multiplication is defined if and only if the inner dimensions match:
$$\text{Matrix } A_{(m \times k)} \times \text{Matrix } B_{(k \times n)} = \text{Matrix } C_{(m \times n)}$$
- The number of columns in $A$ must equal the number of rows in $B$.
- The resulting matrix $C$ takes its row count from $A$ and its column count from $B$.
    A (m × k)         B (k × n)         C (m × n)
┌              ┐   ┌              ┐   ┌              ┐
│              │   │              │   │              │
│   m rows     │ × │   k rows     │ = │   m rows     │
│              │   │              │   │              │
└              ┘   └              ┘   └              ┘
    k cols             n cols             n cols
        ▲                 ▲
        └───── MATCH ─────┘
[!WARNING] Matrix multiplication is not commutative: in general, $AB \neq BA$. Even when both products exist (e.g., when multiplying square $n \times n$ matrices), the resulting matrices are rarely identical.
The Step-by-Step Row $\times$ Column Method
To find the entry $c_{ij}$ in the $i$-th row and $j$-th column of product $C$, compute the scalar dot product of Row $i$ of matrix $A$ and Column $j$ of matrix $B$:
$$c_{ij} = \sum_{p=1}^k a_{ip} b_{pj} = a_{i1}b_{1j} + a_{i2}b_{2j} + \dots + a_{ik}b_{kj}$$
2x2 Worked Example
Let $A = \begin{bmatrix} 2 & 3 \ 1 & 4 \end{bmatrix}$ and $B = \begin{bmatrix} 5 & 1 \ 0 & 2 \end{bmatrix}$.
-
Calculate $c_{11}$ (Row 1 of $A$ $\cdot$ Column 1 of $B$):
$c_{11} = (2 \cdot 5) + (3 \cdot 0) = 10 + 0 = 10$ -
Calculate $c_{12}$ (Row 1 of $A$ $\cdot$ Column 2 of $B$):
$c_{12} = (2 \cdot 1) + (3 \cdot 2) = 2 + 6 = 8$ -
Calculate $c_{21}$ (Row 2 of $A$ $\cdot$ Column 1 of $B$):
$c_{21} = (1 \cdot 5) + (4 \cdot 0) = 5 + 0 = 5$ -
Calculate $c_{22}$ (Row 2 of $A$ $\cdot$ Column 2 of $B$):
$c_{22} = (1 \cdot 1) + (4 \cdot 2) = 1 + 8 = 9$
Resulting product:
$$AB = \begin{bmatrix} 10 & 8 \ 5 & 9 \end{bmatrix}$$
The Determinant Product Theorem: $\det(AB) = \det(A)\det(B)$
One of the cornerstone properties in linear algebra states that for any two $n \times n$ square matrices $A$ and $B$:
$$\det(AB) = \det(A) \cdot \det(B)$$
Mathematical Proof Verification using our Example:
Let us evaluate each determinant using our Determinant Calculator 2x2:
- $\det(A) = (2 \cdot 4) - (3 \cdot 1) = 8 - 3 = 5$
- $\det(B) = (5 \cdot 2) - (1 \cdot 0) = 10 - 0 = 10$
- Product of individual determinants: $\det(A) \cdot \det(B) = 5 \cdot 10 = 50$
- Direct determinant of $AB$:
$\det(AB) = (10 \cdot 9) - (8 \cdot 5) = 90 - 40 = 50$
The equality $\det(AB) = \det(A)\det(B) = 50$ holds true.
Crucial Algebraic Properties of Matrix Multiplication
When manipulating algebraic expressions or matrices, keep these rules in mind:
| Property | Formula | Determinant Relationship |
|---|---|---|
| Associative Law | $(AB)C = A(BC)$ | $\det(ABC) = \det(A)\det(B)\det(C)$ |
| Distributive Law | $A(B + C) = AB + AC$ | $\det(A + B) \neq \det(A) + \det(B)$ (Determinants are not additive) |
| Identity Element | $A \cdot I = I \cdot A = A$ | $\det(I) = 1 \implies \det(AI) = \det(A)$ |
| Scalar Multiplication | $(c A) B = c(AB)$ | $\det(c A) = c^n \det(A)$ for $n \times n$ matrix |
| Transpose Rule | $(AB)^T = B^T A^T$ | $\det(A^T) = \det(A) \implies \det((AB)^T) = \det(AB)$ |
| Inverse of a Product | $(AB)^{-1} = B^{-1} A^{-1}$ | $\det(A^{-1}) = \frac{1}{\det(A)}$ |
For an in-depth breakdown of all 10 fundamental determinant rules, check our tutorial on Matrix Determinant Properties.
Why Isn’t Matrix Determinant Additive?
A very common mistake students make is writing $\det(A + B) = \det(A) + \det(B)$. This is false.
Consider: $$A = \begin{bmatrix} 1 & 0 \ 0 & 0 \end{bmatrix}, \quad B = \begin{bmatrix} 0 & 0 \ 0 & 1 \end{bmatrix}$$
- $\det(A) = 0$
- $\det(B) = 0$
- $A + B = \begin{bmatrix} 1 & 0 \ 0 & 1 \end{bmatrix} = I_2 \implies \det(A + B) = 1 \neq 0 + 0$
While determinants distribute over matrix multiplication ($\det(AB) = \det(A)\det(B)$), they do not distribute over matrix addition.
Frequently Asked Questions (FAQs)
What happens if you multiply a matrix by its inverse?
By definition, $A \cdot A^{-1} = I$. Applying the determinant product rule: $$\det(A \cdot A^{-1}) = \det(A) \cdot \det(A^{-1}) = \det(I) = 1$$ This yields the classic identity $\det(A^{-1}) = \frac{1}{\det(A)}$. This is also why a matrix is invertible if and only if $\det(A) \neq 0$, as explained in our Invertible Matrix Theorem guide.
Can you multiply two non-square matrices and take a determinant?
If $A$ is $m \times k$ and $B$ is $k \times m$ with $m \neq k$, the product $AB$ is an $m \times m$ square matrix, so its determinant $\det(AB)$ exists. Under the Cauchy-Binet Formula, if $m > k$, $\det(AB) = 0$. If $m \leq k$, $\det(AB)$ equals the sum of products of corresponding minors.
Related Mathematical Resources
Essential matrix guides, determinant theorems, and computational tutorials
- • Sarrus' Rule Shortcut – Master the visual diagonal method for rapid manual 3x3 matrix determinant evaluations without expansion errors. Sarrus rule for 3x3 determinants .
- • LU Decomposition Method – Learn how partial pivoting and triangular factorization compute matrix determinants with high numerical stability. LU decomposition determinant calculation .
- • Cramer's Rule Guide – Step-by-step guide to solving simultaneous linear equations using coefficient matrix determinant ratios. Cramer's rule linear systems .